
Walk past an airport exchange counter, and currencies can look as if they belong on a scoreboard. One British pound may buy more than one US dollar, while it can take well over a hundred Japanese yen to buy that same dollar. At first glance, it is tempting to conclude that the pound is “strong,” the yen is “weak,” and the countries behind them can be ranked in the same way. Economically, that conclusion would be misleading.
The numerical price of one unit of money tells us surprisingly little by itself. Currency strength is shaped by inflation, interest rates, productivity, international trade, capital movements, investor confidence, foreign-exchange reserves, central-bank credibility and expectations about the future. A currency may rise while parts of its economy are struggling, or fall while the country remains productive and prosperous.
Understanding why some currencies gain value while others lose it therefore requires looking beyond the exchange-rate board and asking a more important question: what makes people, businesses, investors and governments want to hold one currency rather than another?
What Does Currency Strength Actually Mean?
An exchange rate is simply the price of one currency expressed in another. When a currency becomes more valuable relative to another currency, it has appreciated; when its value falls, it has depreciated. Understanding currency strength, however, requires more than comparing two exchange-rate numbers.
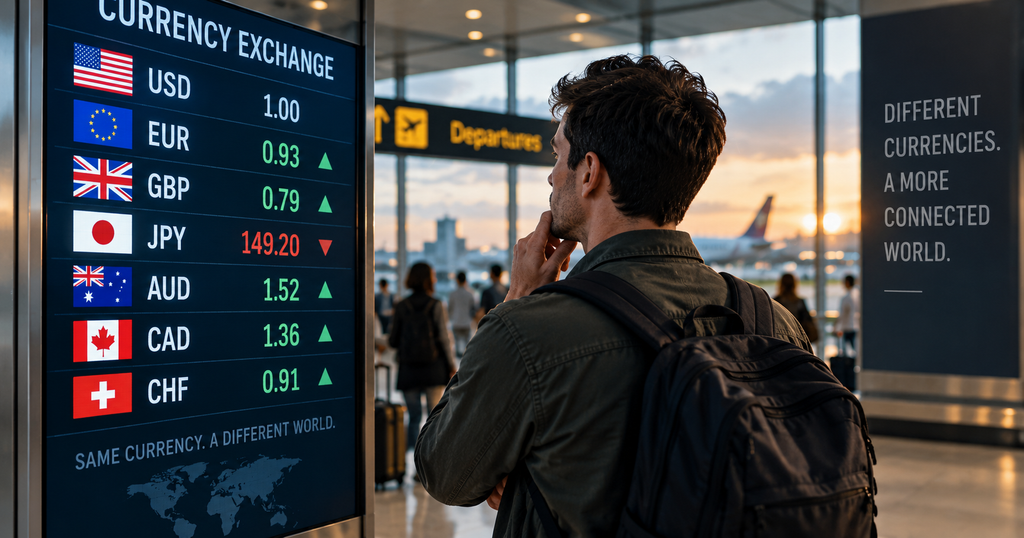
But comparing currencies only against the US dollar can give an incomplete picture. Economists also use trade-weighted measures that compare a currency against baskets of currencies belonging to important trading partners. They may then adjust those measures for differences in inflation to assess changes in international competitiveness. The Bank for International Settlements, for example, distinguishes between nominal effective exchange rates and real effective exchange rates, with the latter incorporating relative price changes.
This distinction matters because a currency can appreciate against one currency while weakening against several others. It can also rise in nominal terms while domestic inflation erodes some of that gain in real purchasing power.
A High-Priced Currency Is Not Necessarily a Stronger Currency
One of the biggest misconceptions about money is that a currency must be stronger simply because one unit buys more dollars. Under that logic, a currency worth several dollars would automatically represent a stronger economy than a currency requiring 100 or 1,000 units to buy a dollar.
The problem is that the size of a monetary unit is largely a matter of denomination. Countries began with different currency denominations, and some have redenominated their money by removing zeros without making the underlying economy richer. A government could replace 1,000 units of an old currency with one unit of a new currency tomorrow; the number on the exchange-rate screen would change dramatically, but productivity, national wealth, and living standards would not suddenly multiply.
Japan illustrates why this distinction matters. The yen’s relatively low value per individual unit does not mean Japan’s productive capacity, technology, companies, or accumulated wealth can be judged by that number. Currency strength should be evaluated through economic fundamentals and changes in purchasing power, not through the size of the denomination alone.
1. Inflation Can Gradually Erode Currency Strength
Inflation is one of the most important long-term influences on the value of money. When prices in one country continually rise faster than prices in its trading partners, the domestic currency loses purchasing power more rapidly.
Imagine two countries selling similar products internationally. If prices in Country A rise substantially faster than prices in Country B year after year, Country A’s products can become less competitive unless productivity improves or its exchange rate adjusts. Currency depreciation can eventually make those products cheaper again for foreign buyers.
However, inflation does not mechanically cause an immediate currency decline. Markets also care about expectations. A temporary inflation shock in a country with a credible central bank may be viewed very differently from persistent inflation in an economy where investors doubt policymakers’ ability or willingness to control prices. For this reason, confidence in future inflation can matter almost as much as today’s inflation rate.
2. Interest Rates Can Pull International Money Across Borders
Interest rates influence the returns available on deposits, government bonds, and other financial assets. If investors can earn a better risk-adjusted return in one country than another, capital may move toward the higher-returning market.
Those investors often need the country’s currency to buy its assets, creating additional demand that can support the exchange rate. This helps explain why foreign-exchange markets pay such close attention to decisions by the US Federal Reserve, European Central Bank, Bank of England and other monetary authorities.
Yet the simple rule that “higher interest rates create a stronger currency” does not always work. Investors compare relative interest rates, inflation expectations and risk. A country offering extremely high rates because inflation is out of control or investors fear a financial crisis may struggle to attract stable capital. Federal Reserve research also shows that unexpected changes in interest-rate differentials can matter significantly because markets often incorporate anticipated policy changes before they happen. What matters is not merely the interest rate advertised today, but what investors expect to earn after inflation, currency movements, and risk are taken into account.
3. Trade Creates Demand for Currencies
Every international transaction has a currency side. Importers need money to pay foreign suppliers, while exporters earn income from overseas customers. Countries that sell competitive goods and services abroad can therefore generate substantial international demand connected to their economies.
A major manufacturing exporter may receive large foreign earnings, while an economy specialising in technology, financial services, tourism, energy or agriculture can create similar flows through different industries. Strong exports may therefore support a country’s external financial position.
But international trade cannot explain exchange rates by itself. Today’s currency markets are also shaped by enormous movements of investment capital. A country may export more than it imports and still experience depreciation if investors simultaneously move substantial amounts of money abroad. Trade flows matter, but capital flows can sometimes move faster and on a much larger financial scale.
4. Productivity Gives a Currency Stronger Foundations
Over the long term, one of the healthiest foundations for an economy is productivity: the ability to generate more valuable output from available workers, capital, knowledge and resources.
A productive economy can support higher wages and profits without relying entirely on higher prices. Competitive companies may expand internationally, while foreign businesses may want to invest in factories, technology, shares, infrastructure and new enterprises within the country.
Those investment flows can increase demand for the domestic currency. Strong education, infrastructure, institutions, innovation, and efficient businesses therefore influence currencies indirectly by making an economy more attractive and capable of producing sustainable income.
This also explains why rapid GDP growth alone does not guarantee long-term currency strength. Growth built predominantly on excessive borrowing, speculative asset prices, or unsustainable external deficits can eventually produce vulnerabilities. How an economy grows can matter more than how fast it grows for a few years.
5. Confidence Can Move a Currency Before Economic Data Does
Money ultimately depends on trust. Investors want confidence that contracts will be enforced, financial institutions will function, inflation will remain manageable, and governments can meet their obligations without repeatedly destabilising the monetary system.
When that confidence deteriorates, foreign investors may withdraw capital and domestic savers may attempt to protect their wealth by moving into foreign currencies. That can place further downward pressure on the exchange rate, sometimes creating a difficult cycle in which depreciation itself increases fear.
The opposite can happen in countries regarded as financially and institutionally stable. The Swiss franc, for example, has historically attracted demand during periods of global uncertainty. Investors seeking relative safety may buy certain currencies even when the issuing country’s economy is not experiencing extraordinary growth. That reveals an important feature of foreign-exchange markets: currencies are influenced not only by economic performance, but also by perceptions of risk.
6. Some Currencies Have Global Demand That Others Do Not
The world’s currencies do not begin on equal terms. Some are used extensively outside the countries that issue them. The US dollar is the clearest example. It plays a major role in international trade, financial markets, cross-border borrowing, and central-bank reserves. The euro is another major reserve currency, while the Japanese yen, British pound, Swiss franc, and several other currencies also have international financial roles.
This creates demand that goes beyond buying products from the issuing country. A central bank may hold dollars as reserves, a multinational company may borrow in dollars, and international transactions may be priced in dollars even when no American company is involved.
IMF reserve data continue to show the scale of this advantage: in the first quarter of 2026, the US dollar represented 57.13% of reported global foreign-exchange reserves, far ahead of any other individual currency. Reserve-currency status does not guarantee permanent appreciation, but it demonstrates why two countries with similar growth rates can still experience very different levels of global demand for their currencies.
7. Central Banks Can Influence Exchange Rates but Not Without Limits
Governments use different exchange-rate systems. Some currencies float relatively freely according to market supply and demand, while others are managed within certain ranges or linked more closely to another currency.
Central banks can influence their currencies through interest rates, foreign-exchange intervention and other monetary policies. They may also use foreign-exchange reserves to reduce disorderly market movements or meet international payment needs.
Large reserves can provide valuable financial protection, particularly when a country needs to pay for essential imports or external debt during periods of stress. However, reserves are finite. If authorities repeatedly sell foreign currency to defend an exchange rate that investors no longer believe is sustainable, the intervention can become increasingly expensive. A government can influence the price of its currency, but it cannot permanently escape the underlying economic realities of inflation, productivity, external financing, and confidence.
Currency Markets Often Move on Tomorrow’s News Today
Perhaps the most confusing part of exchange rates is that markets frequently react before the economy itself changes. Suppose investors become convinced that a central bank will raise interest rates three months from now. Many will not wait three months before adjusting their investments. They may buy the currency immediately, meaning part of the expected policy change appears in today’s exchange rate.
The same principle works in reverse. A central bank can announce an interest-rate increase and still see its currency fall if investors had expected an even larger increase. Good economic news can produce little movement when markets already anticipated it, while unexpectedly bad news can cause an immediate reaction. Exchange rates therefore reflect not only reality, but the gap between reality and expectations. This is one reason short-term currency movements can appear disconnected from economic headlines.
Is a Strong Currency Always Good?
A rising currency sounds positive, but appreciation creates both winners and losers. Consumers may benefit because imported fuel, food, medicines, electronics, machinery, and other foreign products become cheaper in domestic-currency terms. Overseas travel becomes more affordable, businesses using imported components face lower costs, and cheaper imports may help reduce inflation.
Exporters can experience the opposite effect. Greater currency strength can lower import costs, but it can also create difficulties for businesses selling abroad. Their products become more expensive for foreign customers, potentially making it harder to compete internationally. Tourism may also become more expensive for overseas visitors, while domestic manufacturers can face greater competition from cheaper imports.
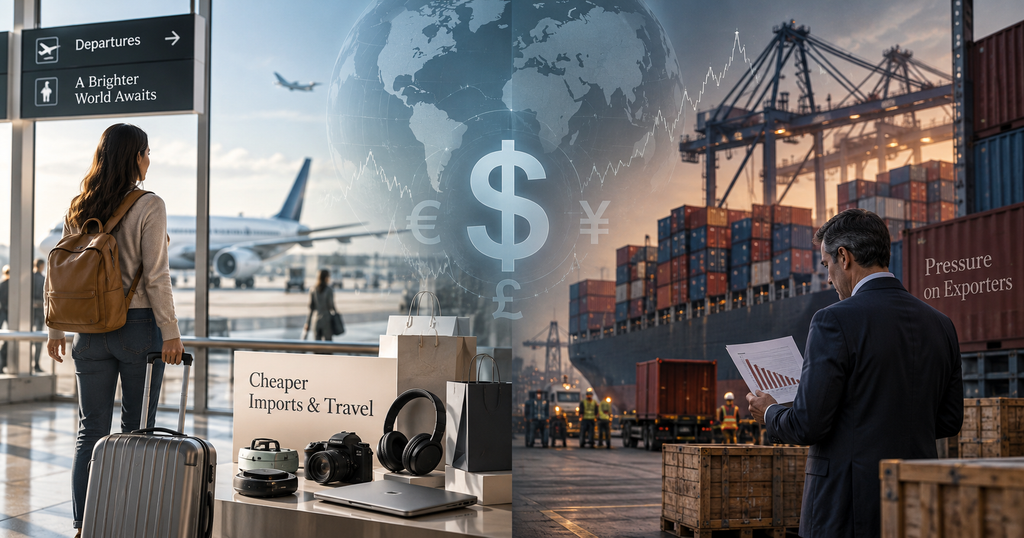
A weaker currency reverses many of those effects. Exporters and tourism businesses may become more competitive, but imported necessities become more expensive. Countries dependent on imported energy, machinery or food can feel the effects quickly, while governments and companies with debts denominated in foreign currencies may face much higher repayment costs. For these reasons, the goal of economic policy should not simply be to create the strongest currency possible. Stability, credibility and sustainability can be more valuable than strength alone.
What Really Makes a Currency Strong?
There is no single ingredient. Sustainable currency strength usually rests on a combination of relatively controlled inflation, productive economic activity, credible institutions, manageable external obligations, functioning financial markets, and confidence that policymakers will protect the monetary system over time.
Even then, currencies will fluctuate. Trade cycles change, commodity prices move, financial markets become more or less willing to take risks, and central banks adjust policies as economic conditions evolve.
The better way to judge a currency is therefore not to ask whether its individual units look expensive or cheap. The better questions are whether its purchasing power is reasonably stable, whether people trust it, whether the economy behind it remains productive, and whether its value can be maintained without unsustainable economic sacrifices.
Final Thought
Currencies are often treated as national scoreboards, with appreciation celebrated as success and depreciation interpreted as failure. Economics is rarely that simple. A currency can become too strong for exporters, weaken during a healthy economic adjustment or temporarily rise because international investors are frightened by events elsewhere.
What matters is the foundation underneath the exchange rate. Productive businesses, sustainable growth, controlled inflation, credible institutions and public confidence give a currency something that central-bank intervention alone cannot manufacture indefinitely: trust.
In the end, the strongest currency is not necessarily the one with the highest number on an exchange board. It is the one people believe will continue to function as a reliable store of purchasing power, means of payment, and foundation for economic activity not just today, but years into the future.
Author’s Note
This article is intended for general educational and informational purposes and does not constitute financial, investment, foreign-exchange, tax, or economic-policy advice. Currency values can change rapidly and are influenced by economic, financial, institutional, and geopolitical conditions that vary significantly among countries. Readers are not required to agree with the author’s interpretation and are encouraged to consider alternative economic perspectives, updated data, and country-specific circumstances before drawing conclusions. The author writes from a background in accounting, finance and economics, with the aim of explaining complex financial and economic issues in clear, practical language for an international readership.