

Government debt is one of the most misunderstood parts of modern economics. Some headlines treat rising national debt as evidence that a country has spent beyond its means, while others suggest governments can continue borrowing almost indefinitely. Neither view captures the full picture because the consequences of debt depend on far more than the amount owed.
Governments borrow to finance infrastructure, respond to economic shocks, support public services, and cover periods when spending exceeds revenue. The International Monetary Fund estimated that global public debt reached just under 94% of world GDP in 2025 and projected it to reach 100% by 2029. That does not mean a global debt crisis is inevitable, but it does make understanding how government debt works increasingly important. (IMF)
1. Why Do Governments Borrow Money?
Governments borrow partly because revenue and spending rarely match perfectly from year to year. Large projects such as transport systems, energy infrastructure, schools, hospitals, and water networks can provide benefits for decades, so financing part of their cost over time may be economically reasonable.
Borrowing can also help during recessions, natural disasters, financial crises, wars, or other emergencies. Revenue may fall precisely when governments need to spend more, making temporary borrowing a way to avoid immediate large tax increases or abrupt reductions in essential services.
This is also where an important distinction is often missed. A budget deficit is the amount by which government spending exceeds revenue during a particular year, while government debt is the accumulated amount borrowed over time to finance past deficits and other financing needs. Repeated deficits generally add to the debt stock, although the precise relationship can also be affected by other government financing transactions. (Congressional Budget Office)
2. Who Actually Lends Money to Governments?
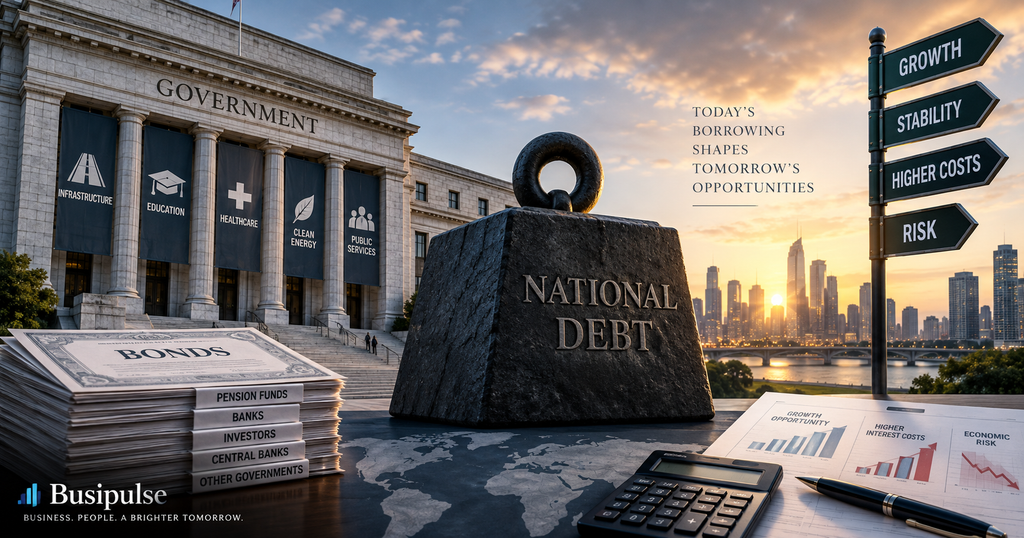
Most governments borrow by issuing securities such as treasury bills, notes, and bonds. Buyers can include banks, pension funds, insurers, investment funds, individual investors, foreign institutions, central banks, and other governments.
Developing economies may also borrow from institutions such as the World Bank, regional development banks, and the International Monetary Fund. The important point is that not all debt is alike: interest rates, repayment periods, currencies, creditor types, and refinancing conditions can differ substantially.
Government borrowing through bonds should also not be confused with simply creating new money. Fiscal borrowing and monetary policy can interact, particularly when central banks operate in government-bond markets, but issuing debt and expanding the money supply are not the same process.
3. Government Debt Is Not the Same as Household Debt
Comparing a national government directly with a household can be misleading. A household usually plans to repay a mortgage or other loan within a defined period, while governments can continue collecting taxes, issuing securities, and refinancing maturing debt over very long periods.
When a government bond reaches maturity, the government may repay it from available funds or issue new debt to replace it. This process, known as refinancing or rolling over debt, is a normal part of public finance. Countries therefore do not generally operate with the objective of reducing all government debt to zero.
The more relevant question is whether debt can continue to be financed at an affordable cost without placing excessive pressure on future budgets. This resembles a point discussed in Busipulse’s earlier examination of where household money actually goes: borrowing can finance useful assets, but it also creates claims on future income. Governments operate under very different financial conditions, yet affordability still matters.
4. Why Debt-to-GDP Does Not Tell the Whole Story
Debt-to-GDP compares government debt with the size of the economy supporting it. It is useful, but there is no single percentage at which every country suddenly enters a debt crisis.
Japan demonstrates why. The IMF projected Japan’s gross public debt at approximately 203% of GDP in 2026, yet assessed its overall sovereign-debt-distress risk as moderate. Among the mitigating factors identified by the IMF were Japan’s relatively favourable debt maturity structure, deep domestic investor base, the yen’s reserve-currency role, and significant public-sector financial assets. The IMF also warned that rising interest and ageing-related costs create longer-term fiscal challenges. (https://www.imf.org/en/publications/cr/issues/2026/04/02/japan-2026-article-iv-consultation-press-release-staff-report-and-statement-by-the-575112?)
The example does not mean very high debt is harmless. It shows why the structure behind the headline number matters. Another useful measure is the debt-service burden — how much government revenue must be devoted to interest and repayments. A country whose debt ratio appears manageable can still face pressure if borrowing costs rise sharply or large amounts of debt must be refinanced within a short period.
This connects with the broader argument in BusiPulse’s Rich Country, Poor Country analysis: productive capacity matters. An economy generating stronger income and revenue growth generally has greater capacity to carry financial obligations than one in which debt rises while the economic base supporting it stagnates. (BusiPulse)
5. Why Foreign-Currency Government Debt Can Be Riskier
The currency in which debt is owed can fundamentally change the risk. If a government borrows in dollars, euros, or another foreign currency and its domestic currency loses value, the local-currency cost of servicing that debt can rise even though the amount originally borrowed has not changed.
World Bank analysis of low- and middle-income countries illustrates this problem: currency depreciation has increased the local-currency burden of foreign debt service across many economies because substantial portions of their external liabilities are denominated in foreign currencies. (World Bank Blogs)
Pakistan provides a useful contemporary example without implying that all of its public debt is external. Pakistan’s Ministry of Finance reported that, at the end of December 2025, total public debt stood at about PKR 81.4 trillion, of which approximately 32% was external debt. External public debt was reported at about US$92.9 billion. The same Debt Bulletin noted that a large majority of external debt was medium- or long-term, which helps reduce refinancing pressure compared with heavier dependence on short-term commercial borrowing.
Pakistan’s example therefore demonstrates both sides of the issue. Foreign-currency obligations create exchange-rate and foreign-exchange requirements, but the maturity and creditor structure of that debt also influence the degree of risk.
6. When Does Government Debt Become Dangerous?
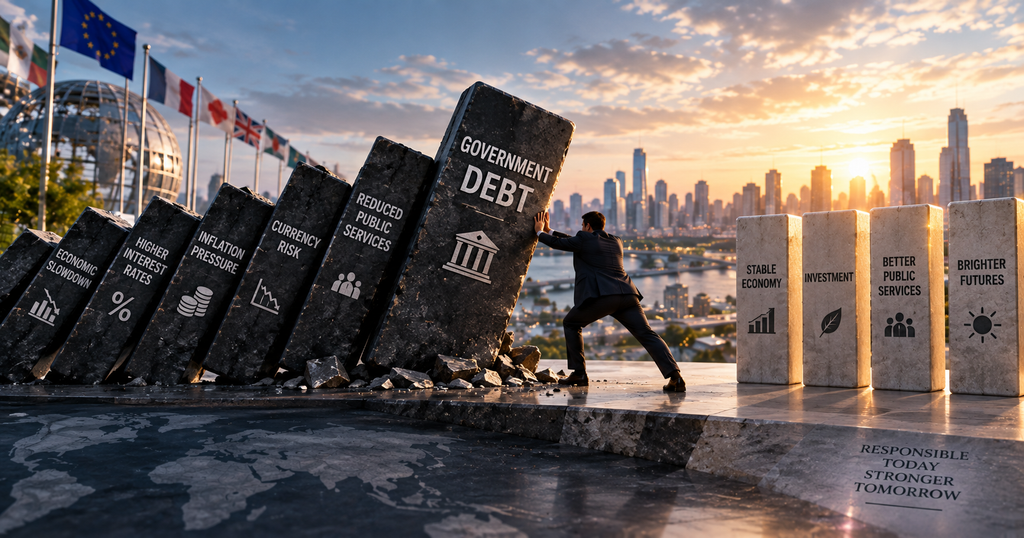
Government debt rarely becomes dangerous simply because it crosses one particular percentage of GDP. Problems are more likely when several weaknesses begin reinforcing one another: borrowing costs rise, economic growth weakens, government revenue becomes insufficient, debt maturities shorten, foreign-currency exposure becomes difficult to manage, or investors become less willing to refinance existing obligations.
Short-term debt can be particularly vulnerable because it must be refinanced more frequently. Foreign-currency debt introduces exchange-rate risk, while rapidly rising interest costs can consume a growing share of government revenue. The IMF’s debt-management guidance therefore treats interest-rate, exchange-rate, and rollover risks as important components of sovereign debt management rather than focusing only on the total debt stock. (IMF)
Greece provides a historical example of how confidence and financing conditions can interact. During the euro-area sovereign-debt crisis, borrowing costs rose to levels that effectively prevented Greece from financing itself sustainably in private markets, leading to international financial assistance. Conditions have subsequently improved considerably: the European Stability Mechanism reported in 2026 that Greek sovereign yields had moved much closer to those of other European economies following years of economic recovery and fiscal improvement. (ESM)
Advanced economies are not exempt from debt pressure. In its February 2026 baseline, the U.S. Congressional Budget Office projected federal debt held by the public to rise from about 101% of GDP in 2026 to 120% in 2036, while net interest spending was projected to increase from 3.3% to 4.6% of GDP. These are projections rather than predetermined outcomes, but they illustrate how higher interest costs can gradually reduce the room available for other budget priorities even when a government retains strong access to financial markets. (Congressional Budget Office)
7. What Makes Government Borrowing More Sustainable?
Sustainable borrowing depends partly on what borrowed money ultimately produces. Debt used effectively for infrastructure, energy systems, education, technology, or other productive investment can strengthen an economy’s future capacity, although even productive projects must still be financed and managed carefully.
Governments can also reduce vulnerability by extending debt maturities, limiting excessive foreign-currency exposure, developing deeper domestic financial markets, improving revenue collection, maintaining credible institutions, and avoiding persistent dependence on borrowing simply to cover structural imbalances.
There is no universal debt level that is safe for every country. The stronger approach is to examine the debt together with economic growth, government revenue, interest costs, maturity dates, currency exposure, foreign-exchange resources where relevant, and continued access to financing.
Final Thoughts
Government debt is neither free money nor automatically a national disaster. It can help countries build productive assets, respond to emergencies, and support an economy during difficult periods, but it also creates future financial obligations that eventually have to be serviced.
That is why two countries with similar debt-to-GDP ratios can face very different risks. Japan, the United States, Greece, Pakistan, and other economies differ in their currencies, financial markets, investor bases, debt maturities, foreign-exchange positions, institutions, and economic capacity.
Perhaps the most useful question is therefore not simply, “How much government debt is too much?” A better question is whether borrowing today strengthens an economy’s ability to meet tomorrow’s obligations or merely pushes an increasing financial burden into the future. Debt can provide governments with valuable financial capacity, but it cannot permanently substitute for productivity, credible institutions, sufficient revenue, and sustainable economic growth.
Author’s Note
My professional background in financial administration and accounting procedures has shaped my interest in understanding how governments raise, manage, and account for public money. Government debt is often discussed through political arguments or dramatic headline figures, but its economic consequences depend on financing costs, maturity structures, currency exposure, public revenue, economic growth, and how borrowed funds are ultimately used.
This article examines government borrowing from an economic and financial perspective rather than advocating a particular government, political system, or public-policy programme. Readers are not required to agree with the author’s interpretations or conclusions and are encouraged to examine the evidence, consider alternative economic perspectives, and form their own views.
The information presented here is intended for general educational purposes and should not be considered financial, investment, tax, legal, or public-policy advice. At Busipulse, the aim is to make complex economic and financial issues easier to understand without removing the complexity that genuinely matters.
[…] energy, machinery or food can feel the effects quickly, while governments and companies with debts denominated in foreign currencies may face much higher repayment costs. For these reasons, the goal of economic policy should not […]