
A change in the quantity of a product or service available in a market rarely happens without a reason.
A coffee shop may sell more cups after lowering its price. A construction company may offer fewer services when labor costs rise. Demand for air conditioners can increase during a heat wave, while a shortage of components can reduce the number of products manufacturers are able to produce.
These situations may look unrelated, but they are connected by one of the most basic ideas in economics: supply and demand.
The question “What factors impact the quantity of a product or service?” sounds simple, but the answer depends on whether we are talking about quantity demanded, quantity supplied, or the equilibrium quantity sold in a market.
Understanding that distinction matters not only to economics students. It matters to entrepreneurs, retailers, investors, and business owners trying to understand why customers buy more or less and why businesses increase or reduce production.
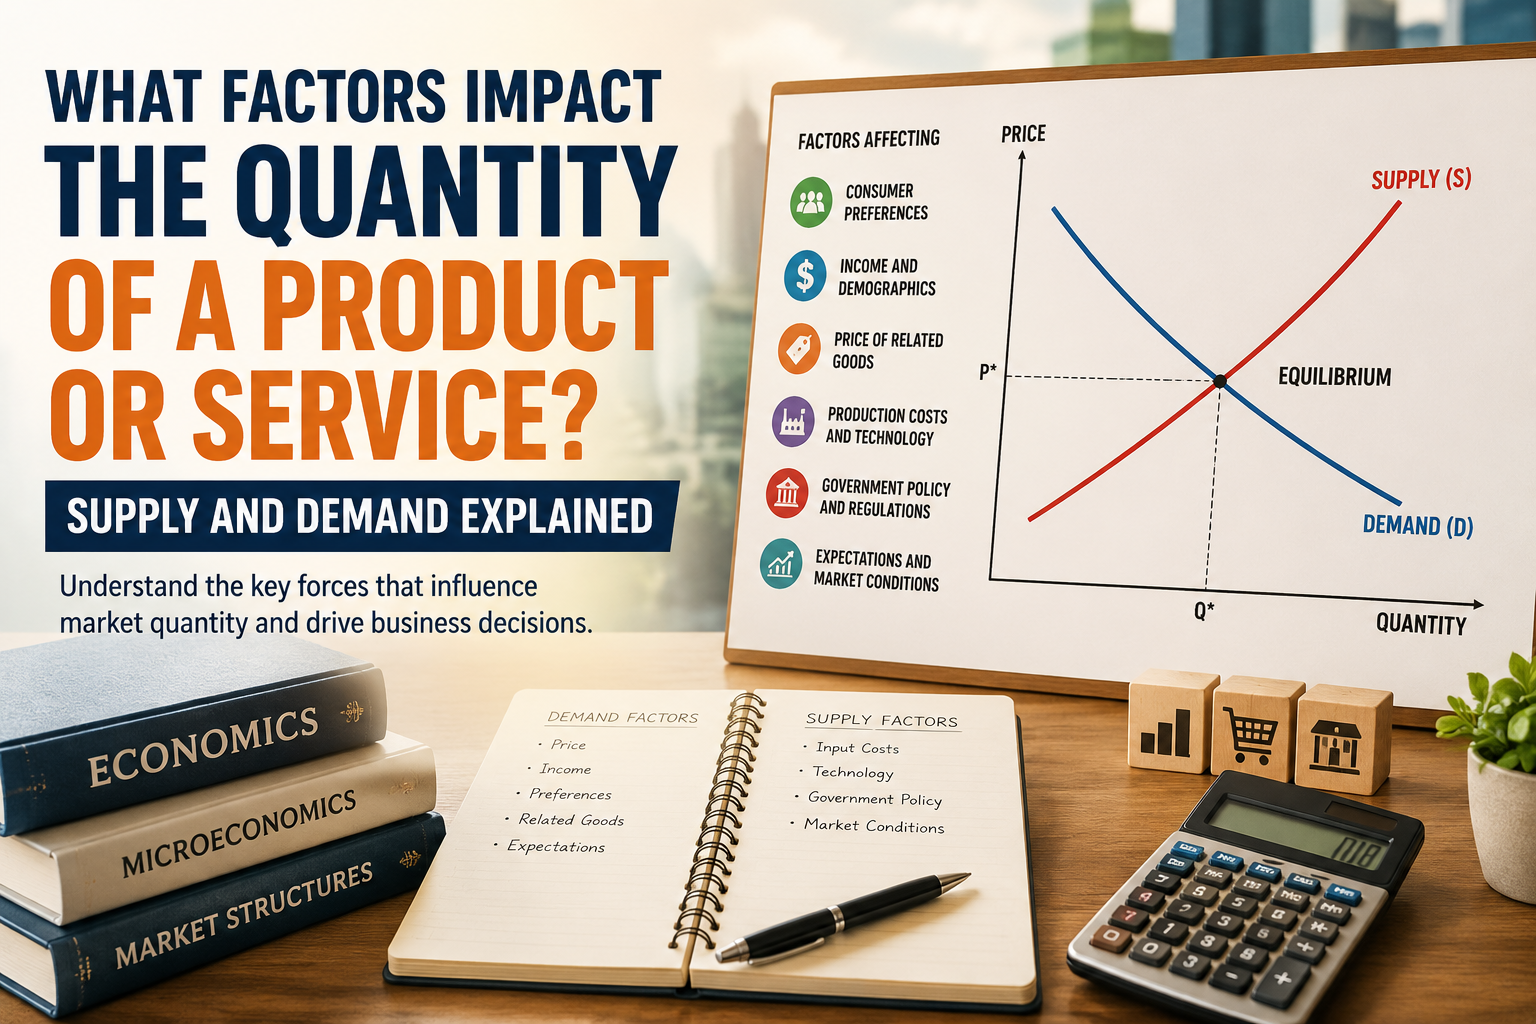
The quantity of a product or service available in a market can change for several reasons, including changes in prices, costs, consumer preferences, and other market conditions.
What Does “Quantity” Mean in Economics?
In everyday language, people often use “demand” and “quantity demanded” as if they mean the same thing. Economists make a sharper distinction.
Quantity demanded is the amount of a product or service consumers are willing and able to purchase at a particular price.
Quantity supplied is the amount producers are willing and able to sell at a particular price.
Demand and supply are broader concepts. Demand describes the relationship between price and the quantities consumers are willing and able to buy, while supply describes the relationship between price and the quantities producers are willing and able to sell. OpenStax makes the distinction between demand and quantity demanded particularly clear: demand refers to the broader relationship, while quantity demanded refers to a specific point on that relationship. (OpenStax) That distinction leads to an important question:
What actually causes quantity to change?
1. Price Is a Major Factor Affecting Quantity Demanded
For most ordinary products and services, price is an important influence on how much customers buy. When the price of a product falls, consumers generally have an incentive to purchase more. When the price rises, they generally purchase less, assuming other relevant conditions remain unchanged. This is known as the law of demand. Consider a simple example.
Suppose a restaurant normally sells a particular meal for $15. If the price falls to $10, some customers who considered the meal too expensive may decide to buy it. Existing customers may also purchase it more frequently.
The quantity demanded has increased because the product’s price changed.
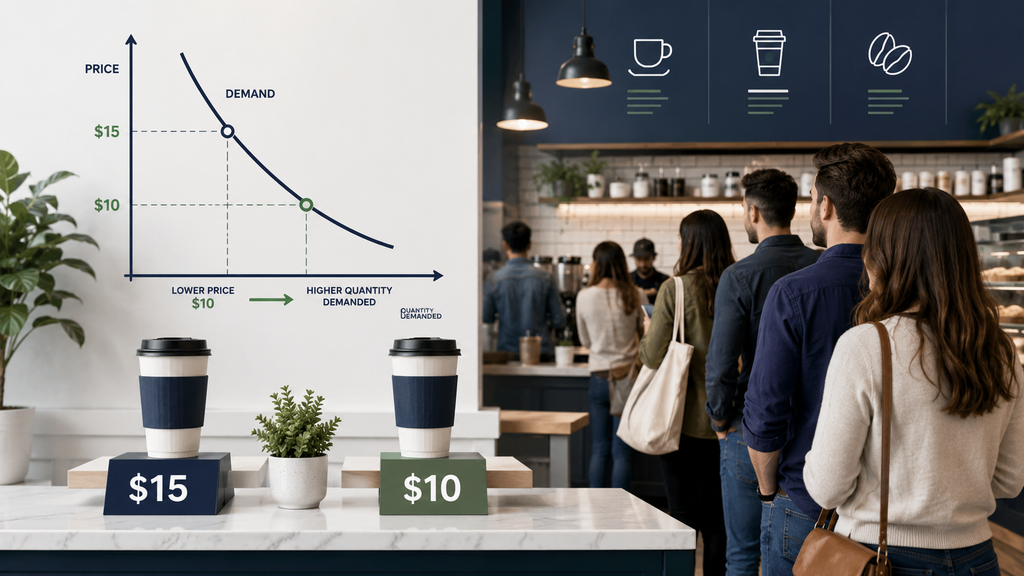
The opposite can happen when prices rise. A customer who regularly buys a service for $50 may reduce purchases if the price increases to $80.
For quantity demanded, the product’s own price is the primary factor that causes movement along the demand curve, assuming other relevant factors remain unchanged. OpenStax explains that a change in the price of the good itself changes quantity demanded rather than shifting the demand curve. (OpenStax)
However, the relationship is not identical for every product. Some goods and services are highly sensitive to price, while others are relatively resistant to price changes. Economists study this responsiveness through price elasticity of demand.
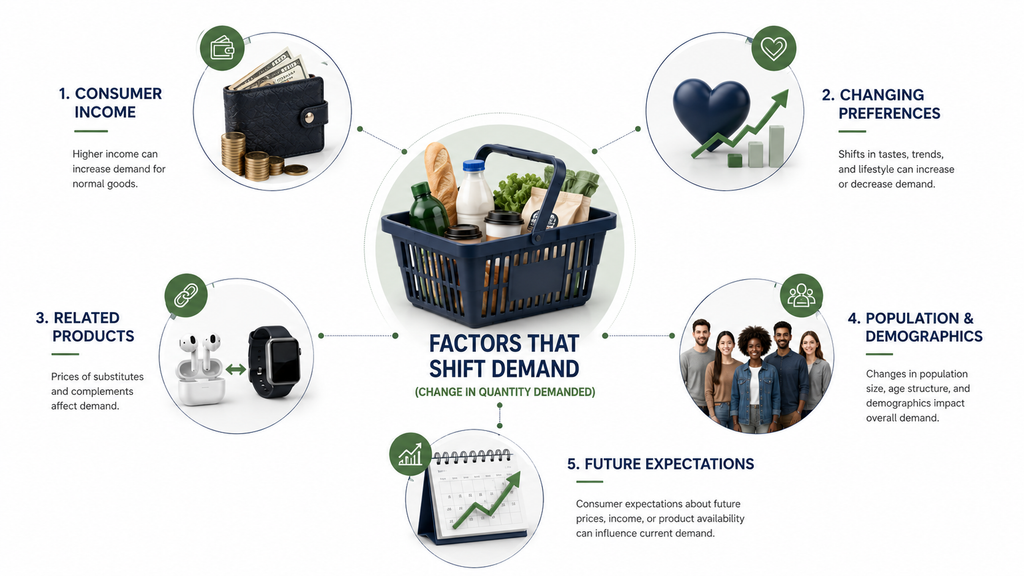
2. Consumer Income Can Change Demand
Price is not the only factor that influences how much consumers purchase. Income matters too. When household incomes increase, people may purchase more restaurant meals, travel services, better housing, electronics, entertainment, or other goods. When incomes decline, spending on some products and services may fall. The effect is not identical for every product.
For example, a person receiving a significant income increase may move from budget accommodation to a higher-quality hotel. They may also eat at restaurants more frequently.
But some products can behave differently. Consumers may switch from premium products to cheaper alternatives when their financial situation deteriorates.
For businesses, this means that understanding who the customer is can be just as important as understanding the product.
A company selling premium furniture, for example, should pay attention not only to its own prices but also to the financial conditions of its target market. Income is one of the standard factors economists identify as capable of shifting demand. (OpenStax)
3. Consumer Preferences Can Shift Demand
People’s tastes and preferences change constantly.
Health trends can increase demand for certain foods. Fashion can make particular styles more popular. Social media can suddenly make a product highly desirable. Changing lifestyles can increase demand for convenience services.
Imagine that consumers become increasingly interested in healthier food. A restaurant offering low-sugar meals, high-protein options, or plant-based dishes may see demand increase even if its prices remain unchanged. This is different from a simple price-driven movement along the demand curve. The underlying demand itself has changed. Economists therefore treat tastes and preferences as factors that can shift the demand curve. (OpenStax)
For entrepreneurs, this is one reason market research matters. A product can be well made and reasonably priced but still struggle if customer preferences are moving in another direction.
4. Prices of Related Products Matter
A product rarely exists in isolation. Consumers often have alternatives, and some products are used together. Economists generally divide these relationships into substitutes and complements.
Substitutes
A substitute is a product that can serve a similar purpose. Tea and coffee are common examples. If coffee becomes substantially more expensive while tea prices remain stable, some consumers may purchase more tea.
Complements
Complementary products are used together. Cars and gasoline are an obvious example. Smartphones and mobile data services are another. If the cost of owning or using one product changes significantly, demand for its complement can also change.
Businesses therefore need to watch the wider market, not just their own pricing. A company may keep its prices unchanged while demand changes because the price of a competing or complementary product has moved. Prices of related goods are among the established factors that can shift demand. (OpenStax)
5. Population and Customer Demographics Can Change Demand
Markets change when the number and characteristics of potential customers change. A growing population can create greater demand for housing, transportation, food, healthcare, education, and other services. But population size is only part of the story.
Age, household size, income levels, location, and lifestyle can all influence what people buy.
A city with a rapidly growing young population may create opportunities for restaurants, rental housing, entertainment, delivery services, and digital businesses.
An area with a growing elderly population may generate stronger demand for healthcare, assisted living, mobility services, and home maintenance.
This is why businesses should avoid thinking about “the market” as one enormous group of identical consumers. Markets are made up of people with different needs and purchasing power. Population size and composition are recognized factors that can influence demand. (OpenStax)
6. Expectations About the Future Can Affect Quantity Today
What consumers and businesses expect to happen next can influence what they do now. Suppose customers expect the price of a popular electronic product to rise sharply next month. Some may purchase the product today rather than waiting. The opposite can happen if customers expect prices to fall.
Businesses also make decisions based on expectations.
A retailer expecting strong demand during a holiday period may increase inventory in advance. A manufacturer expecting weak demand may reduce production. Expectations can therefore influence both sides of the market. They are particularly important in industries where purchasing decisions involve significant amounts of money or long planning periods. Expectations about future conditions and prices are among the factors that can shift demand. (OpenStax)
7. Production Costs Affect Quantity Supplied
So far, most of the discussion has focused on customers. But businesses determine how much they are willing and able to supply, and their costs matter.
Imagine a furniture manufacturer whose timber costs rise sharply. If selling prices remain unchanged, the company’s profit margin may shrink. The manufacturer might respond by reducing production, raising prices, finding another supplier, or changing the product. Labor costs, energy prices, raw materials, transportation, rent, financing, and other operating expenses can all affect supply.
OpenStax identifies changes in input costs as one of the factors that can shift the supply curve because they affect how much firms are willing to supply at a given price.
(OpenStax) This has a direct business implication:
A rise in sales does not automatically mean a business should produce more. If the cost of serving additional customers becomes too high, expanding output may actually reduce profitability.
8. Technology Can Increase the Quantity Businesses Supply
Technology can change the economics of production. A manufacturer that introduces more efficient machinery may be able to produce more units at a lower cost.
A logistics company using better route-planning software may be able to serve more customers with the same number of vehicles.
A bookkeeping firm using automation may handle more clients without increasing staff at the same rate.
Technology can therefore increase productive capacity or reduce the cost of supplying a product or service.
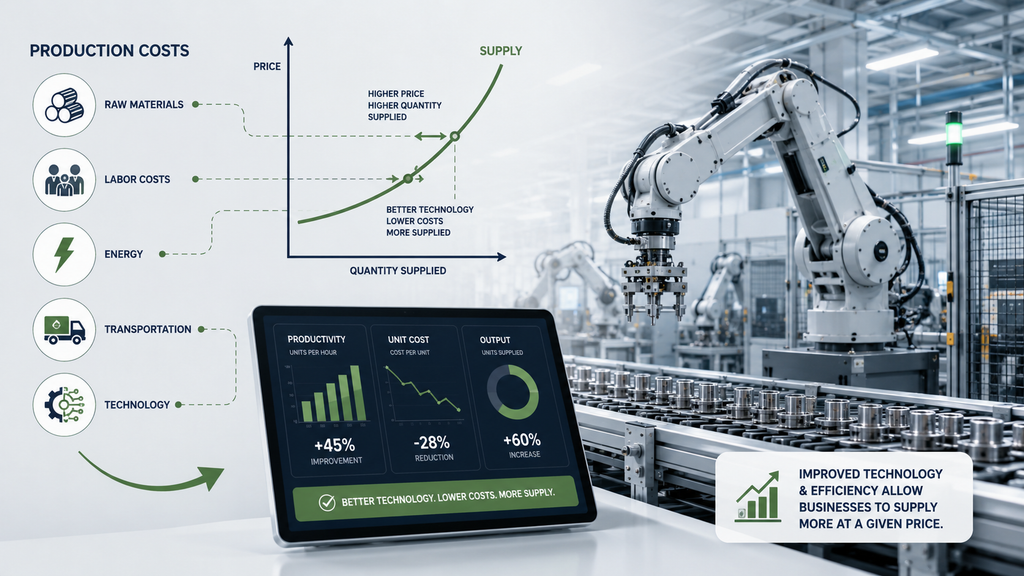
This is one reason technological change can shift supply rather than simply changing the quantity supplied at a particular price. OpenStax identifies new technologies as one of the factors that can affect supply.
(OpenStax) The effect is not limited to factories. For modern service businesses, software, automation, artificial intelligence, and digital platforms can all change how much work a team can handle.
9. Government Policies Can Affect Supply
Taxes, regulations, subsidies, licensing requirements, and other government policies can influence business costs and therefore supply.
For example, a new environmental regulation may require manufacturers to invest in equipment or change production processes. That could increase production costs.
On the other hand, a subsidy may reduce the effective cost of production and encourage businesses to supply more. The effect depends on the specific policy and industry.
For entrepreneurs, the lesson is straightforward: regulation is part of the business environment. Before entering a market, it is worth understanding which licenses, taxes, standards, and compliance requirements apply. OpenStax identifies taxes, regulations, and subsidies among government decisions that can affect supply. (OpenStax)
Quantity Demanded vs. Demand: Why the Difference Matters
This is where many explanations of the topic become confusing. Suppose the price of a product falls and customers buy more. That is a change in quantity demanded.
Now suppose the price stays the same, but the product becomes more popular because consumer preferences have changed. That is a change in demand.
The distinction may seem technical, but it is useful. A business owner who sees sales increasing should ask:
Did customers buy more because our price changed, or because something else changed in the market?
The answer can affect the next business decision. If sales increased only because of a temporary discount, the company may not be able to maintain the same volume at the original price. If demand has genuinely shifted because the product has become more desirable, the opportunity may be much larger.
How Supply and Demand Determine Market Quantity
In a competitive market, buyers and sellers interact to determine an equilibrium price and quantity. The equilibrium quantity is reached where the quantity consumers want to buy matches the quantity producers want to sell.
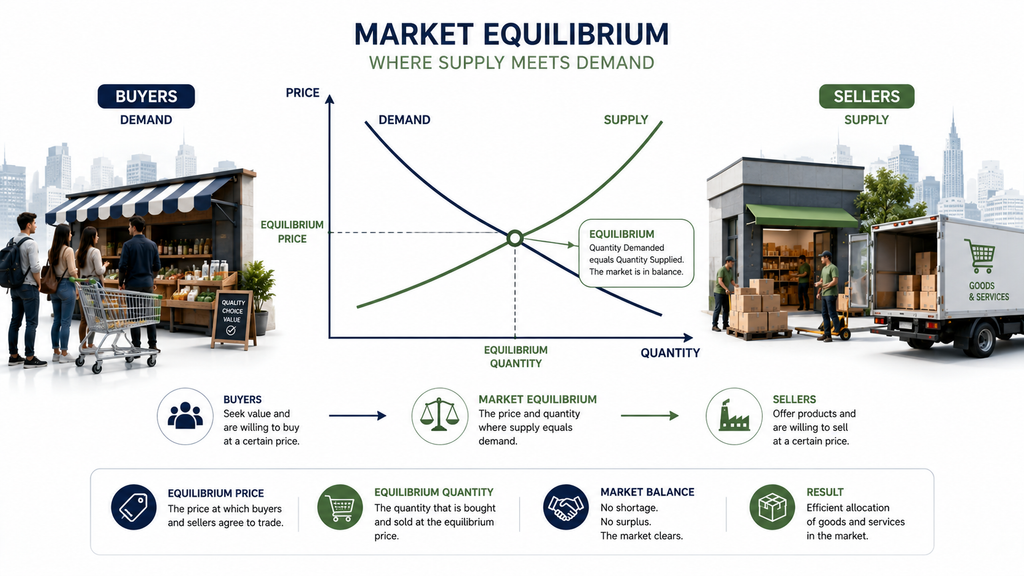
If demand increases while supply remains unchanged, the equilibrium price and quantity will generally rise.
If supply increases while demand remains unchanged, the equilibrium price will generally fall while equilibrium quantity rises. The exact result depends on the size and direction of the changes.
Imagine demand for electric vehicles increases while battery production also expands.
Demand pushes the market toward a higher quantity and potentially higher prices, while increased supply pushes toward greater quantity and potentially lower prices. The final market outcome depends on how strongly each curve shifts. OpenStax defines equilibrium as the point where quantity demanded equals quantity supplied. (OpenStax)
Why This Matters to Business Owners
Supply and demand are not just concepts for economics classrooms. They can help entrepreneurs answer practical questions.
Should you raise your price?
Should you increase inventory?
Is demand temporary or sustainable?
Can your suppliers support higher sales?
Is a competitor changing the market?
Are customers becoming more price-sensitive?
Is a new technology reducing your costs?
These questions are fundamentally about the forces behind quantity, price, demand, and supply. For entrepreneurs considering a new market, the practical lesson is to examine the customer, competition, pricing, market conditions, and the costs of delivering the product or service rather than assuming that rising demand automatically guarantees success.
For example, an entrepreneur considering a property-related business should not look only at whether people “need property.” They should examine local demand, customer characteristics, competition, pricing, and the specific services customers actually want.
For more on opportunities within the property market, see 7 Real Estate Business Opportunities on Busipulse.
A Simple Way to Think About It
When trying to understand why the quantity of a product or service has changed, ask five questions:
1. Did the price change?
If yes, quantity demanded or supplied may have moved along the relevant curve.
2. Did customer preferences change?
If yes, demand may have shifted.
3. Did customer income or demographics change?
If yes, demand may change even if the product’s price remains the same.
4. Did production costs or technology change?
If yes, supply may have shifted.
5. Did government policy, expectations, or market conditions change?
If yes, the market may experience another demand or supply shift.
This simple framework can prevent a common mistake: assuming every change in sales is caused by price. Understanding the forces that influence the quantity of a product or service can help businesses make better decisions about pricing, production, inventory, and expansion.
Final Thoughts
So, what factors impact the quantity of a product or service? There is no single answer.
For quantity demanded, the product’s own price is a central factor. For broader changes in demand, income, preferences, population, related-product prices, and expectations can matter. For quantity supplied, the product’s price, production costs, technology, regulations, and other business conditions can influence how much producers are willing and able to offer. The bigger lesson for entrepreneurs is perhaps the most useful one.
Markets change because people, businesses, costs, technology, and expectations change.
Understanding those forces can help a business owner make better decisions about pricing, inventory, production, marketing, and expansion. The next time sales suddenly rise or fall, don’t stop at asking “What happened to our sales?” Ask a better question:
“What changed in the market that caused customers or suppliers to change their behavior?”
That question can turn a basic economics concept into a practical business tool.
Author’s Disclaimer
This article is intended for general educational and informational purposes only. The views and interpretations expressed here are those of the author and are based on established economic concepts and publicly available information. Readers are not required to agree with the author’s views or interpretations. Economic conditions and business circumstances can vary significantly, and readers should conduct their own research and seek appropriate professional advice when making business or financial decisions.