

For years, blockchain technology was discussed mainly through Bitcoin, cryptocurrencies, and digital speculation. In 2026, however, real-world asset tokenization is attracting growing attention from banks, asset managers, central banks, fintech companies, and institutional investors. Instead of creating an entirely new cryptocurrency, tokenization can digitally represent rights connected to an existing asset, such as a government security, investment fund, corporate bond, property interest, commodity, or private-credit instrument.
That is different from asking what gives cryptocurrency value. A tokenized Treasury security, fund share, bond, or property interest does not become valuable simply because it exists on a blockchain. Its underlying economic value still depends on the asset, issuer, contractual rights, cash flows, market demand, and legal enforceability. Blockchain changes how those rights may be recorded, transferred, settled, and programmed. Real-world asset tokenization is therefore less about replacing finance with cryptocurrency and more about modernizing parts of the infrastructure through which financial assets move.
A simple example makes the idea easier to understand. Imagine a $10 million commercial property held by a company created specifically to own that building. Instead of selling the entire property to one buyer, the company could potentially structure eligible investment interests and represent those interests digitally through blockchain-based tokens. An investor purchasing a token would not necessarily receive their name on the property’s deed; depending on the legal structure, the token might instead represent shares in the company, beneficial rights, income rights, or another contractual interest connected to the property. The blockchain records and transfers the digital representation, while property law and legal agreements determine what the investor actually owns.
What Is Real-World Asset Tokenization?
Real-world asset tokenization, often called RWA tokenization, is the process of representing ownership rights or economic claims associated with an asset through digital tokens recorded on blockchain or distributed-ledger infrastructure. Depending on the structure, a token could represent a fund share, bond, beneficial ownership interest, claim on income, debt obligation, or another legally recognized financial right. The precise legal arrangement behind the token matters just as much as the code that creates it.
Franklin Templeton provides a useful real-world example. Its Franklin OnChain U.S. Government Money Fund uses public blockchain technology in its recordkeeping system, and one share of the fund is represented by one BENJI token. The underlying investment remains a regulated money-market fund investing primarily in U.S. government securities, cash, and fully collateralized repurchase agreements. The blockchain-based token does not turn those government securities into a new cryptocurrency; it provides a digital representation of an investor’s fund share and supports blockchain-enabled transaction and ownership-record functions. Franklin Templeton said in April 2026 that the fund had reached its fifth anniversary and helped pioneer what had become a multibillion-dollar tokenized-fund category.
Why Financial Institutions Are Taking Tokenization Seriously
One reason real-world asset tokenization is attracting financial institutions is its potential to improve operational efficiency. Traditional finance works remarkably well at enormous scale, but its infrastructure can involve multiple databases, custodians, brokers, transfer agents, clearing systems, settlement networks, reconciliation processes, and operating-hour restrictions. Information may need to move through several organizations before a transaction is fully completed. Tokenization offers the possibility of moving selected parts of that process onto shared programmable infrastructure where authorized participants can work from synchronized records.
Consider a corporate bond. Traditionally, issuing and servicing a bond can require several intermediaries and separate systems for issuance, ownership records, payments, and settlement. In 2023, Siemens issued a €60 million digital bond on a public blockchain under Germany’s Electronic Securities Act. Siemens said the structure allowed the security to be sold directly to investors without using established central securities depositories and demonstrated how blockchain infrastructure could make issuance faster and more efficient. It was not a cryptocurrency replacing the bond; it was a conventional corporate financing instrument issued through new digital infrastructure.
That distinction helps explain why institutions are interested. The commercial question is not whether blockchain sounds innovative; it is whether tokenized assets can reduce friction, improve settlement, automate repetitive processes, or make capital easier to move. If the economics are better than existing systems and regulatory requirements can still be satisfied, tokenization starts becoming an infrastructure decision rather than a technology experiment.
Which Real-World Assets Are Being Tokenized?
The market for real-world asset tokenization now spans several categories of traditional financial and physical assets. Tokenized U.S. Treasuries and money-market funds have become some of the clearest early applications because they combine familiar financial assets with blockchain-based ownership and transfer infrastructure. In August 2026, BlackRock expanded its cash-management business with two tokenized money-market products in the United States. It also introduced tokenized access to selected institutional money-market funds in Europe, illustrating how major asset managers are exploring blockchain infrastructure while retaining regulated investment structures.
The concept can extend much further. Real estate tokenization could represent legally structured interests in commercial buildings, residential developments, or property funds. Private-credit tokens could represent claims connected to loans. Commodities could be represented through tokens tied to properly custodied underlying assets, while bonds and investment funds can use blockchain-based ownership records and settlement. BlackRock currently identifies tokenized Treasury funds as one of the asset categories demonstrating meaningful market traction, while many other categories remain much earlier in their development. That is an important reminder that the potential market is large, but adoption is uneven.
Suppose, for another simplified example, a private-credit fund contains loans to dozens of businesses. Rather than changing those loans into cryptocurrencies, a regulated structure could issue tokenized fund interests to eligible investors. Smart contracts might assist with transfer restrictions, distributions, or reporting while the borrowers continue making ordinary loan repayments. Tokenization changes the financial wrapper and infrastructure around the investment; it does not magically change the economic risk of the loans themselves.
How Tokenization Works in Practice
A serious real-world asset tokenization project begins with the asset, not the token. The issuer first determines exactly what investors are buying and what rights accompany it. Lawyers and financial professionals may establish the ownership structure, custody arrangements, investor eligibility requirements, disclosures, compliance rules, transfer restrictions, and redemption process. Only then does blockchain infrastructure become useful for representing and administering those rights digitally.
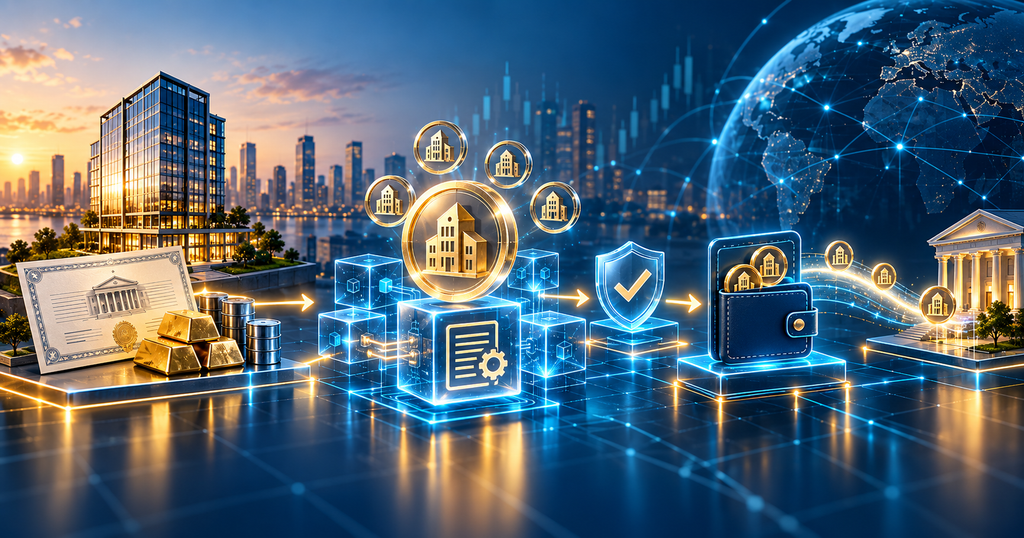
For example, if a fund offers tokenized shares, an approved investor might purchase a share and receive the corresponding token in an authorized digital wallet. When ownership is transferred, the blockchain can record the transaction while the fund’s official ownership records are updated according to the applicable structure. BlackRock describes its tokenized money-market funds as traditional funds whose shares are represented digitally, with features that can include approved-wallet transfers, programmable workflows, and blockchain-enabled ownership records.
This is why simply creating a token does not create meaningful asset tokenization. The difficult part is connecting digital records with enforceable legal rights and reliable financial infrastructure. Investors still need answers about custody, bankruptcy protection, redemption, valuation, regulatory status, taxation, reporting, and dispute resolution. A professionally tokenized asset therefore combines software with legal, compliance, financial, cybersecurity, and operational systems.
How Tokenization Could Make Financial Markets More Efficient
One of the strongest arguments for tokenization involves settlement. In many financial transactions, the asset and the payment pass through different systems, creating periods during which capital remains tied up, and counterparties remain exposed to one another. Tokenized infrastructure can support atomic settlement, where the transfer of an asset and the corresponding payment are coordinated so that both occur together or neither occurs.

Imagine Institution A buying a tokenized bond from Institution B. Instead of one system recording the bond transfer and another separately processing payment, programmable infrastructure could potentially exchange the security and settlement asset as parts of one coordinated transaction. This does not eliminate every financial risk, but it can reduce certain settlement risks and operational delays. The European Central Bank has specifically highlighted atomicity and programmability as important potential benefits of tokenized wholesale finance.
Automation may provide another advantage. Smart contracts can potentially handle functions such as coupon payments, investor eligibility rules, ownership restrictions, collateral movements, distributions, and redemptions according to predefined conditions. That could reduce manual processes and reconciliation costs, particularly in markets where administration remains fragmented.
Fractional Ownership Could Change Access, but Not Automatically Liquidity
Tokenization is frequently associated with fractional ownership because digital systems can make it technically easier to divide an economic interest into smaller units. A commercial property worth millions of dollars, for instance, could potentially be held through a structure that allows investors to purchase smaller economic interests rather than financing an entire building themselves. Similar structures could theoretically be applied to private funds, infrastructure projects, commodities, and other high-value assets.
However, fractionalization and liquidity are not the same thing. Dividing a $10 million asset into 100,000 digital units does not guarantee that 100,000 buyers will appear. Investors still need a legally compliant marketplace, transparent pricing, reliable information, willing counterparties, and confidence that they can exercise the rights represented by their tokens. Tokenization can make an asset easier to divide and potentially easier to transfer, but it cannot manufacture genuine market demand.
The Business Opportunity May Be Bigger Than the Tokens
For entrepreneurs and technology companies, one of the most commercially interesting aspects of real-world asset tokenization is that the opportunity extends far beyond issuing tokens. A functioning tokenized financial market requires digital custody, secure wallets, identity verification, anti-money-laundering systems, investor onboarding, legal technology, smart-contract auditing, blockchain analytics, cybersecurity, asset servicing, valuation data, accounting tools, tax reporting, payment infrastructure, portfolio management, interoperability, and compliance software.
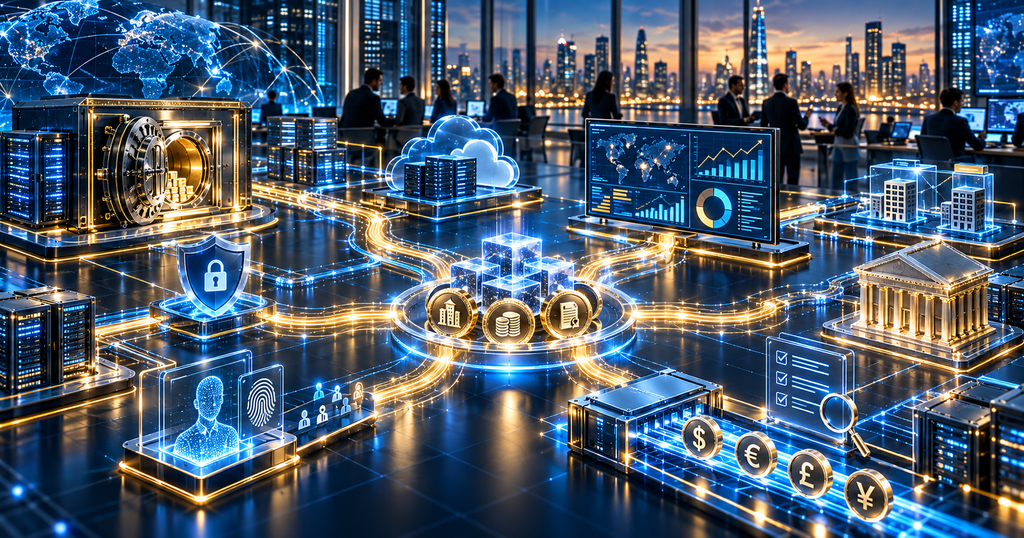
This resembles earlier financial technology shifts. Some highly successful businesses did not profit primarily from owning financial assets; they built the infrastructure that enabled other businesses to move money, accept payments, manage investments, verify customers, or comply with regulations. If tokenized finance expands, a similar opportunity could emerge around the companies providing the secure tools institutions need to operate. For B2B software companies, fintech platforms, cybersecurity providers, and data businesses, the infrastructure surrounding tokenization may eventually be more commercially attractive than speculation on individual tokens.
What Could Go Wrong With Real-World Asset Tokenization?
Tokenization does not remove financial risk. A tokenized bond issuer can still default. A tokenized commercial property can lose tenants and decline in value. A tokenized private-credit portfolio can suffer borrower defaults. A tokenized fund can experience losses. The efficiency of the blockchain infrastructure should never be confused with the quality of the underlying investment. Putting a weak asset on sophisticated technology does not turn it into a strong asset.
There are also technology and legal risks. Smart contracts can contain bugs, wallets can be compromised, cybersecurity systems can fail, incorrect data can enter automated processes, and different blockchain networks may struggle to communicate with one another. Securities laws, property rights, custody requirements, taxation, bankruptcy treatment, and investor protections also vary significantly between jurisdictions. A token might move globally in seconds while the legal rights attached to it remain subject to national laws that move much more slowly.
This is particularly important with tokenized real estate and other physical assets. If a platform claims that a token represents part of a building, investors should determine what that statement legally means. Does the token represent direct property ownership, shares in a company owning the property, entitlement to rental income, debt secured by the property, or something else entirely? The answer could make an enormous difference if the issuer fails or a dispute occurs.
Why 2026 Matters for Real-World Asset Tokenization
The strongest evidence that tokenization is moving beyond experimentation is not a rising token price but the involvement of major financial institutions and central banks. BlackRock expanded tokenized money-market offerings during 2026, while Franklin Templeton continued developing its blockchain-integrated fund infrastructure. These are established asset managers applying tokenization to regulated financial products rather than launching speculative cryptocurrencies.
The public financial infrastructure is moving as well. On September 21, 2026, the Eurosystem launched Pontes, designed to enable wholesale transactions involving tokenized assets to settle in central bank money. The ECB said the system is part of its strategy for tokenized finance and will expand gradually. The significance is substantial: tokenization becomes more credible for institutional markets when both the asset side and the settlement side can operate within trusted financial infrastructure.
None of this guarantees that every stock, bond, building, or fund will eventually move onto a blockchain. Existing financial systems already perform many functions efficiently, and replacing them only makes economic sense where the benefits outweigh implementation costs and risks. The more realistic future may be a hybrid financial system in which tokenization is used selectively where programmability, faster settlement, collateral mobility, fractionalization, or improved distribution creates measurable value.
Final Thoughts
Real-world asset tokenization matters because it connects blockchain technology with financial assets and ownership rights that already exist. A government security does not need a new source of value simply because its ownership can be represented digitally, and an office building does not become more valuable merely because investors can hold blockchain-based interests connected to it. The real question is whether tokenization can make those assets easier, cheaper, safer, or more efficient to issue, transfer, settle, service, and manage.
For investors, that means examining the underlying asset and legal rights before becoming impressed by the technology. For businesses, however, the opportunity may be considerably broader. Digital custody, compliance, cybersecurity, identity verification, payments, data, smart-contract auditing, accounting, asset servicing, and institutional blockchain infrastructure could all become important commercial markets if tokenized finance continues developing. The long-term winners may therefore include not only organizations tokenizing assets, but also the companies quietly building the infrastructure that allows traditional finance and blockchain systems to work together.
Author’s Note
This article is intended for general educational and informational purposes and does not constitute financial, investment, legal, tax, securities, real-estate, or cryptocurrency advice. Tokenized assets can involve complex ownership arrangements, regulatory requirements, technology risks, market risks, custody structures, and jurisdiction-specific laws. Readers should independently verify what rights any particular token represents before making financial decisions.
Readers are not required to agree with the author’s analysis or conclusions. The purpose of this article is to explain the developing field of real-world asset tokenization in an accessible and balanced manner while recognizing both its potential advantages and its limitations. Businesses and investors considering tokenized assets should seek appropriate professional advice based on their circumstances and applicable jurisdiction.
[…] is also where wrapped cryptocurrency differs from real-world asset tokenization. Wrapped Bitcoin represents an existing digital asset, whereas real-world asset tokenization can […]