

Your salary may be higher than it was a few years ago. Your house may be worth more. Businesses are collecting more dollars in sales, and the economy itself is measured in numbers that seem to keep getting bigger. Yet many people open their bank accounts and feel exactly the opposite of richer. Groceries cost more, housing takes a larger share, insurance bills arrive, debt payments continue, and saving can feel harder than it should.
The question “where is all the money going?” becomes especially frustrating when your income has increased but your financial position does not seem to improve. It is tempting to imagine that the money has disappeared or simply moved into somebody else’s pocket. The reality is more complicated. More dollars moving through an economy do not necessarily mean that each dollar buys as much as it once did or that everybody benefits equally when incomes, prices, and asset values rise. Understanding that difference helps explain why an economy can grow while many households still feel financially squeezed.
The concern is real. In the Federal Reserve’s latest annual household survey, price increases remained the most common financial concern, and 58% of adults said price changes over the previous year had made their financial situation worse.
More Money Doesn’t Always Mean More Buying Power
Suppose you earned $50,000 a year and later received a 10% raise. Your salary is now $55,000. You are earning more dollars, but whether you are actually better off depends partly on what happened to your expenses during the same period.
If housing, food, transportation, insurance, and utilities have also become substantially more expensive, your larger paycheck may not stretch much further. This is the difference between the number of dollars you receive and their purchasing power.
It also explains a common frustration when inflation begins to fall. Imagine something costing $100 and later rising to $110. If inflation then slows considerably, the price does not necessarily return to $100. It may simply increase more slowly from its new level. Lower inflation generally means prices are rising more slowly; it does not necessarily mean prices are falling. That is why improving inflation figures can coexist with shoppers still wondering why everything feels expensive.
Your Paycheck Has More Competition
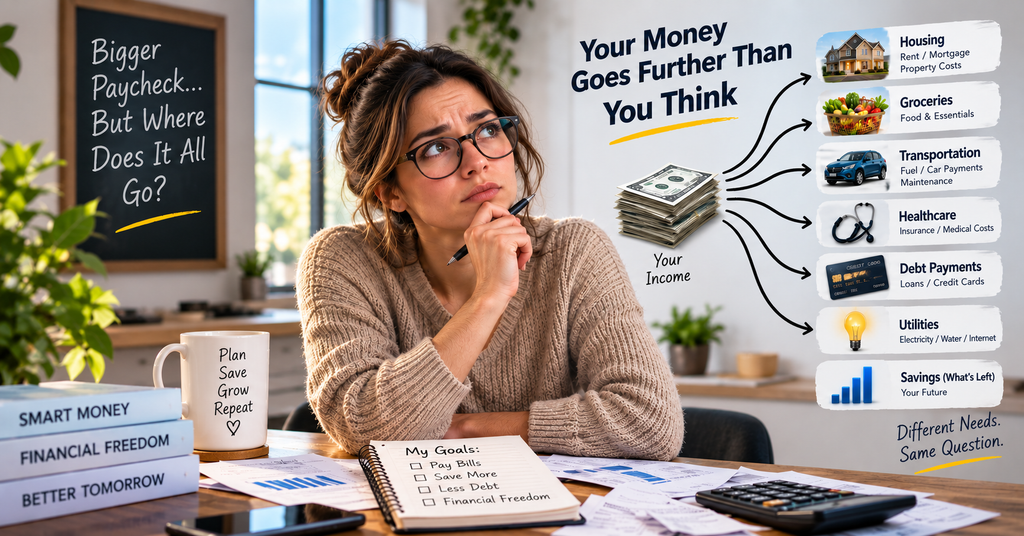
Most households do not experience the economy through GDP figures or inflation charts. They experience it when the bills arrive. Imagine $5,000 entering a household each month. Housing takes a share, followed by food, transportation, utilities, insurance, childcare, taxes, loan payments, and smaller expenses. If several of those costs rise faster than income, the household can earn more and still have less flexibility at the end of the month.
Two families earning the same amount can therefore experience completely different financial situations. One may have a manageable mortgage and little debt. Another may be paying current market rent, financing a car, supporting children, and carrying expensive credit-card balances.
The Federal Reserve’s survey covering households’ financial well-being in 2025 found that 16% of adults had not paid all their bills in the previous month, while 63% said they could cover a hypothetical $400 emergency expense entirely using cash or its equivalent. National statistics can describe the economy accurately without describing your particular household accurately.
Some of Today’s Income Is Paying for Yesterday
Debt adds another pressure because borrowing today places a claim on tomorrow’s income. A mortgage can help a family buy a home. A business loan can finance productive equipment. Education borrowing may help someone develop valuable skills. Debt is not automatically good or bad; its cost, purpose, and affordability matter.
But every required payment reduces the money available for something else. Federal Reserve data show that required household debt-service payments represented about 11.2% of disposable personal income in the first quarter of 2026. This is an economy-wide measure rather than a figure applying equally to everyone, but it illustrates the significance of existing financial obligations. A person can therefore receive a raise and still feel little improvement because some of today’s income is already committed to decisions made yesterday.
Rising House Prices Can Make One Person Richer and Another Feel Poorer
Consider a house purchased years ago for $300,000 that is now worth $450,000. The owner has gained wealth, but an extra $150,000 has not suddenly appeared in the bank account. Much of that increase remains wealth on paper unless the property is sold or its equity is accessed.
Now look at the same house through the eyes of someone trying to buy it today. What represents greater wealth for the existing owner represents a more expensive purchase for the aspiring buyer.
The same principle can apply to shares and other investments. Rising asset values can increase the wealth of people who already own those assets while providing little direct benefit to people who own none. This is one reason prosperity can feel uneven. People can live in the same economy while standing on opposite sides of the same price increase.
The Economy Can Grow Without Everyone Feeling Richer
We often speak about “the economy” as though it were one enormous household. It isn’t. Millions of people earn different incomes, own different assets, carry different debts, live in different places, and buy different things.
A growing economy can therefore coexist with financial stress. Businesses may expand while some households struggle. Wages can rise while important expenses rise faster for particular families. Asset owners can become wealthier while people trying to acquire those assets face higher barriers.
The Federal Reserve’s latest survey illustrates this contrast: about 73% of adults said they were doing okay financially or living comfortably, yet only about one-quarter rated the national economy as good or excellent.
For entrepreneurs, this distinction matters. Higher average incomes do not automatically mean customers have more discretionary money. If housing, food, insurance, or debt payments consume more of their paychecks, they may become more selective about everything else. Understanding the customer’s wallet can sometimes matter as much as understanding the customer’s income.
So Where Does Your Money Actually Go?
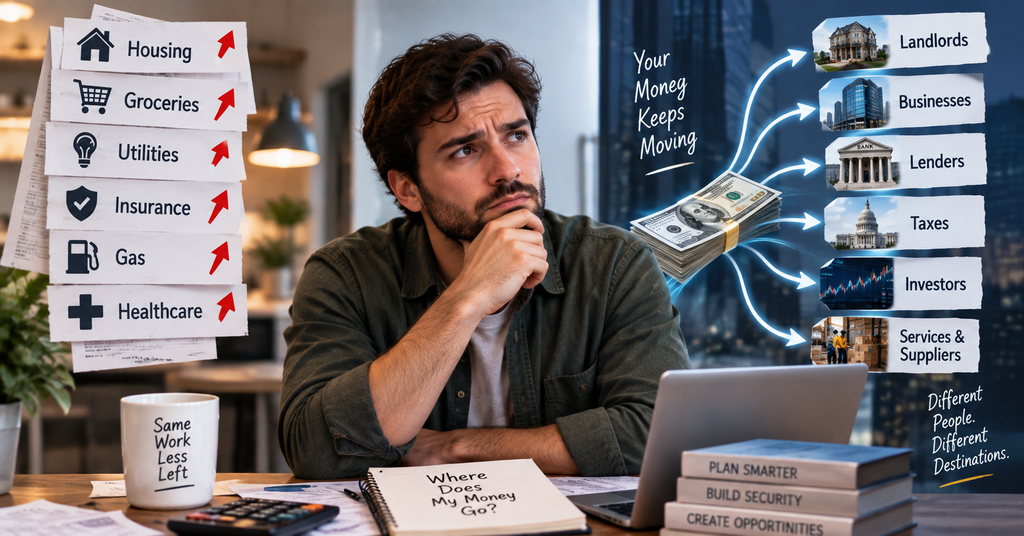
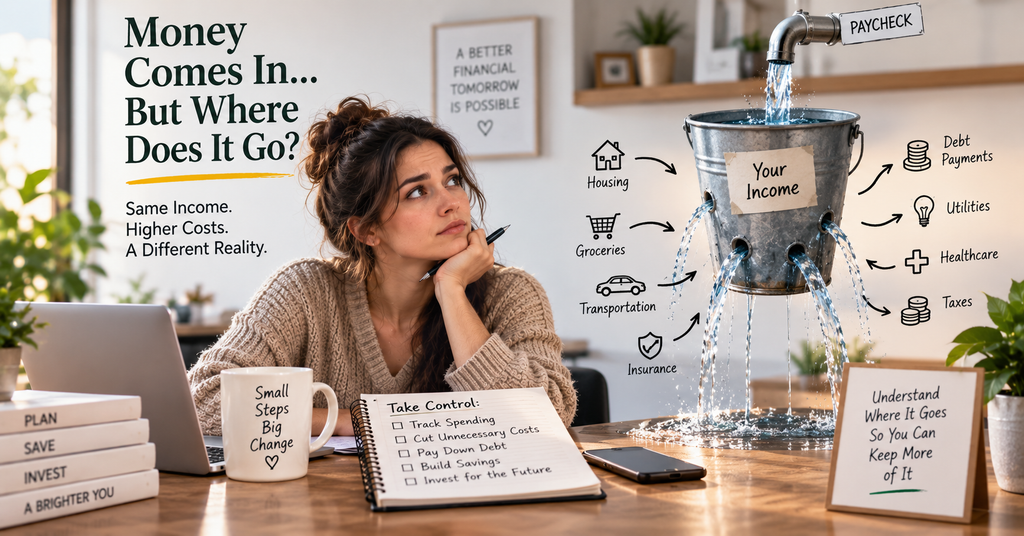
Asking “where is all the money going?” becomes easier to answer when you follow where each payment actually ends up. When you pay rent, somebody receives that rent. When you pay interest, the payment goes to a lender or investor. When you buy groceries, your spending becomes business revenue that helps pay employees, suppliers, landlords, lenders, taxes, and other costs. Money continues moving through the economy, but it does not move equally or necessarily return to the people who originally spent it.
This also affects businesses. Financially pressured consumers may postpone purchases, switch to cheaper alternatives, compare offers more carefully, or demand clearer value. An entrepreneur who recognizes those changes can respond more intelligently than one who simply concludes, “Customers aren’t spending anymore.” That makes understanding what is actually holding a business back especially important before spending more on marketing or changing the offer.
What Can You Do When Money Doesn’t Stretch Far Enough?
You cannot personally control inflation, interest rates, housing markets, or the wider economy. You can, however, understand your own financial position more clearly. Start by identifying where your money actually goes rather than relying on the feeling that it simply disappears. Separate essential expenses from discretionary ones, examine recurring costs, and pay particular attention to expensive debt that continuously claims future income. When income rises, consider directing part of the increase toward reducing high-cost debt, building emergency savings, or acquiring productive assets instead of automatically allowing expenses to rise with the paycheck.
When considering a major purchase, look beyond the monthly payment and examine the total financial commitment. Distinguish an increase in asset value from cash you actually have available to spend.
For entrepreneurs, watch how economic pressure changes customers rather than assuming the answer is always a lower price. Customers may value durability, convenience, smaller packages, flexible payment arrangements, or a clearer reason why a product deserves their limited money.
None of these actions can eliminate wider economic pressures, and households facing low incomes or unavoidable high expenses may have limited room to adjust. But knowing which pressures you can influence is more useful than treating every financial problem as completely beyond your control.
Final Thoughts
If everyone seems to be struggling with money, there is no single place where “all the money” has gone. Some income is absorbed by higher prices, some services past debt, some flows into housing and other assets, and some becomes wages, business revenue, taxes, interest, and investment returns. People who own appreciating assets can experience the same economy very differently from people trying to acquire them.
That is why a bigger salary, a more valuable house, or a growing economy does not automatically create greater financial comfort. What matters to an individual is not simply the number of dollars coming in, but what those dollars can buy, how much is already committed, and what remains afterward.
Perhaps the better question is not simply, “Where did all the money go?” Ask where your money is going, which costs are taking more of it, which decisions remain within your control, and whether today’s spending is strengthening or limiting tomorrow’s financial position. Money may not have disappeared. What changed may be where it goes, what it buys, and who benefits when it moves.
Author’s Note
My professional background in financial administration naturally leads me to look beyond headline numbers when discussing money. Rising income, growing asset values, and economic growth can all be positive developments, but they do not necessarily describe the financial experience of every household.
This article presents an economic perspective rather than a universal explanation of anyone’s personal financial situation. Readers do not need to agree with the author’s conclusions. Inflation, income, housing, debt, and wealth are complex subjects whose effects vary between people and economic circumstances. Readers should conduct independent research and seek appropriate professional advice before making significant financial decisions.
At Busipulse, the aim is to make economics, finance, and business understandable without removing the complexity that matters. Sometimes the most useful starting point is not accepting or rejecting a popular assumption, but asking what is actually happening underneath the numbers.
[…] bears the adjustment costs. This helps explain why stronger headline growth does not always ease household financial pressure for ordinary […]
[…] This distinction matters because national prosperity is ultimately connected to productivity and income per person, not simply the headline size of GDP. Economic growth can improve living standards, but population growth, inflation, employment, and the distribution of income all influence how much of that progress households actually experience. […]
[…] on future budgets. This resembles a point discussed in Busipulse’s earlier examination of where household money actually goes: borrowing can finance useful assets, but it also creates claims on future income. Governments […]