

A worker living abroad sends $500 every month to support family members back home. The money helps cover groceries, education, healthcare, and household expenses. A transfer company advertises a low transaction fee, but the recipient receives less than expected. The difference may come from currency conversion, intermediary banking charges, or deductions applied before the payment reaches its destination. What appeared to be an inexpensive service may not have been the most economical option.
This problem affects migrant workers, international students, freelancers, and businesses making overseas payments. It is particularly important for families receiving remittances in countries such as India, Pakistan, Bangladesh, and Nigeria, where money sent from abroad can contribute significantly to household finances. Repeated charges may gradually reduce the amount available for essential expenses, even when each individual deduction appears modest.
Why are international money transfer fees so high, and how can consumers reduce them? The answer involves more than the advertised transaction fee. Currency exchange, banking arrangements, payment methods, delivery services, and regulatory requirements can all influence costs. Understanding these factors helps people compare providers accurately, avoid unnecessary expenses, and ensure that more money reaches its intended recipient.
Why International Money Transfers Remain Expensive
Domestic payments often move through financial institutions operating within the same currency and national payment system. International transfers can require coordination between different banks, payment networks, currencies, and regulatory authorities. Financial institutions must also verify customers, process transactions securely, manage currency conversion, and comply with applicable financial regulations. These activities create operating expenses, although the amounts charged to consumers also depend on competition and business pricing decisions.
According to the World Bank’s Remittance Prices Worldwide database, the global average cost of sending remittances was approximately 6.36% in the third quarter of 2025. At that rate, the equivalent cost of a $200 transfer would be approximately $12.72. The figure represents an average across monitored services and transfer corridors rather than a universal fee. Actual charges vary according to the countries involved, payment methods, service providers, and transaction amounts.
The issue remains a priority for international financial institutions. In September 2026, the Organisation for Economic Co-operation and Development published guidance emphasizing clearer disclosure of total transaction costs, currency conversion charges, delivery times, and payment tracking. Its findings reinforce an important principle: consumers need to understand the complete cost before deciding which service offers better value.
1. Upfront Transfer Fees: The Most Visible Expense
The upfront transfer fee is usually the first charge consumers encounter when sending money overseas. International money transfer fees may be calculated as a fixed amount, a percentage of the transaction, or a combination of both. Banks and transfer companies can also apply different charges depending on the destination, payment method, delivery speed, and whether promotional pricing applies. Understanding these differences helps consumers evaluate the actual cost of transferring money instead of relying solely on advertised rates.
Fixed fees can be particularly expensive for people sending small amounts. A $5 charge represents 5% of a $100 transfer but only 0.5% of a $1,000 transfer. Someone transferring $100 every week at $5 per transaction would spend $260 annually on upfront charges alone, excluding currency conversion and any additional costs.
This does not mean people should automatically combine several transfers into one large payment. Families may need money at different times, and delaying essential support can create difficulties. The important consideration is whether the provider’s pricing structure suits the sender’s usual amount and frequency.
2. Exchange-Rate Markups: The Less Obvious Cost
Currency conversion is one of the most easily overlooked components of international money transfer fees. A transfer service may advertise a zero-dollar fee while offering an exchange rate less favorable than a reference market rate. The difference, commonly described as an exchange-rate markup or spread, can represent a substantial part of the provider’s revenue.
Suppose the reference exchange rate is 100 units of the recipient’s currency per US dollar, but a transfer service offers 97 units. On a $500 transfer, the recipient receives 48,500 units instead of the 50,000 units implied by the reference rate. The difference is 1,500 units, equivalent to 3% of the reference value. This is a hypothetical example, and real exchange rates change continuously.
A provider charging a visible transaction fee may nevertheless deliver more money than one advertising free transfers. Consumers should therefore compare exchange rates alongside fees rather than judging services by their promotional claims. It is also important to distinguish a provider’s exchange-rate markup from changes in the market value of a currency. As explained in our analysis of currency devaluation and its economic effects, exchange-rate movements can change the purchasing power of international payments and remittances. The relevant question is how much local currency the recipient receives for the total amount paid by the sender.
3. Intermediary Bank Charges: The Cost of Multiple Institutions
Some international bank transfers pass through correspondent banks because the sending and receiving institutions lack a direct payment relationship. These intermediary banks help move funds between financial systems and may charge processing fees, depending on the payment arrangement.
Such charges can be difficult to anticipate when the sending bank does not specify every institution involved. A customer may pay the original bank’s transfer fee but discover that an additional amount has been deducted before the money reaches the recipient. The responsibility for these charges can also depend on the payment instructions and arrangements between participating institutions.
Not every international payment involves separate intermediary deductions. Some specialized transfer services use local settlement networks or alternative arrangements. Nevertheless, customers sending international bank wires should ask whether intermediary charges may apply, particularly when the recipient needs to receive an exact amount.
4. Recipient-Side Charges: When the Beneficiary Also Pays
The receiving institution may impose its own fee for an incoming international transfer. Depending on the service and country, additional charges may apply to bank deposits, currency conversion, or cash collection. These recipient-side deductions can increase the effective international money transfer fees paid across a transaction, even when the sender has already covered the advertised charges. Consequently, the amount received by the beneficiary may be lower than the original payment estimate.
For example, someone paying an overseas university invoice or sending a business payment may expect the full stated amount to arrive. An unexpected deduction could leave the recipient with an insufficient payment, potentially requiring another transfer and additional charges.
Families receiving money through cash-collection networks may also face transportation expenses if the collection point is far from home. While travel costs are not necessarily charged by the payment provider, they affect the practical value of the transfer. Senders should confirm the receiving method and any known deductions before completing important payments.
5. Funding Method Fees: Why Cards Can Cost More
The way a customer pays for a transfer may influence its price. Bank-account transfers, debit cards, credit cards, and cash deposits can carry different charges because they involve different processing arrangements, payment risks, and operating costs.
Credit-card-funded transfers require particular attention. Depending on the card issuer and transaction classification, some may be treated as cash advances, potentially attracting additional fees and interest charges. A transfer that initially appears inexpensive can therefore become costly when the card issuer’s charges are included.
Consumers should compare available funding methods before confirming a payment. A bank-account-funded transfer may cost less when the sender has sufficient funds and does not require immediate delivery. Credit or other expensive payment arrangements should not be selected merely for convenience without understanding the complete cost.
6. Delivery Speed and Collection Methods
International transfer services offer different delivery options, ranging from near-instant payments to transactions requiring several business days. Faster delivery may cost more, particularly where the provider uses additional services or offers immediate access to funds. However, higher charges do not guarantee that a transfer will arrive without delay.
Processing times can be affected by banking hours, public holidays, customer verification, incorrect information, and additional compliance checks. The delivery method also matters. Bank deposits, digital wallets, and cash collection may have different prices, transaction limits, and accessibility.
For urgent medical or family expenses, paying more for a reliable, faster service may be reasonable. Routine monthly remittances may not require premium delivery. Consumers should choose according to their actual needs rather than assuming that the fastest option is always the best.
7. Taxes, Regulatory Requirements, and Local Restrictions
Cross-border payments must comply with financial laws in the countries involved. Providers may be required to verify customers, monitor transactions, maintain records, and apply measures against fraud, money laundering, and other financial crimes. These obligations create operating expenses, although the cost passed to customers varies between institutions.
Some transactions may also be affected by applicable taxes, currency restrictions, or additional documentation requirements. Such conditions differ considerably between countries and payment types. Regulatory compliance expenses should not automatically be confused with a separately charged government tax.
Limited competition and weak financial infrastructure can also contribute to higher prices. Where customers have few licensed providers or limited access to digital payment systems, cheaper alternatives may be difficult to obtain. These structural challenges help explain why sending identical amounts can cost substantially more through some international payment corridors than others.
How to Calculate the True Cost of Sending Money Abroad
The most reliable way to compare international money transfer fees is to begin with the same total sending budget, destination, currency, and delivery method. Rather than examining the advertised transaction fee alone, consumers should calculate how much money will actually reach the beneficiary after currency conversion and applicable deductions. This approach provides a clearer comparison between providers and helps identify services that offer better overall value.
Consider two hypothetical providers offering transfers within a total budget of $500. Provider A deducts a $5 fee and offers 97 units of local currency per dollar. The remaining $495 converts into 48,015 local currency units. Provider B deducts a $10 fee but offers 99 units per dollar, converting the remaining $490 into 48,510 units. Provider B charges more upfront yet delivers 495 additional units to the recipient.
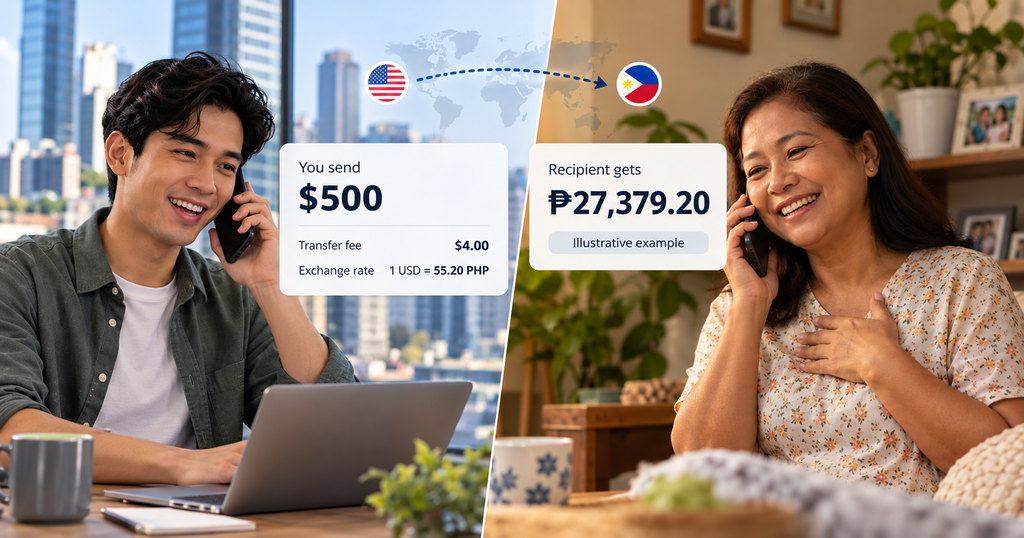
This calculation assumes there are no further deductions. In practice, customers should compare quotations obtained at approximately the same time because exchange rates fluctuate. They should also confirm whether the displayed recipient amount is guaranteed or estimated and whether receiving institutions can impose additional charges.
The comparison demonstrates why total cost matters more than a single advertised price. A low transaction fee does not necessarily mean a cheaper transfer, and an attractive exchange rate may not compensate for substantial additional charges.
Why Transfer Costs Matter to Families in Developing Economies
International remittances help support households across Asia, Africa, Latin America, and other regions. Workers living in Gulf countries, Europe, North America, and elsewhere frequently send money to relatives for everyday expenses, education, healthcare, housing, and savings. The economic significance of these payments varies by country and household circumstances.
India, Pakistan, Bangladesh, and Nigeria provide important examples of countries with substantial international remittance activity. However, their payment networks, exchange-rate conditions, banking access, and migration patterns are different. A transfer from the United Arab Emirates to Pakistan may have different costs from one sent from the United Kingdom to India or the United States to Nigeria.
Repeated expenses can be particularly important for families operating within limited budgets. Saving $10 on a monthly transfer amounts to $120 over a year, provided the lower-cost service remains dependable and suitable. The objective should not be to select the cheapest advertised provider at any cost, but to minimize unnecessary charges while maintaining security and reliable delivery.
Banks, Fintech Companies, and Stablecoins: Which Are Cheaper?
Traditional banks, specialized money transfer companies, and newer digital payment systems use different arrangements to move money internationally. Banks may offer established relationships, account integration, and business payment services, while fintech operators can sometimes reduce costs through local banking connections, digital processing, and alternative settlement structures. The growing integration of financial services into digital platforms is also changing how consumers and businesses access payment facilities. Our article on embedded finance and digital payment services explains how banking, payments, and other financial functions are becoming part of everyday software platforms, creating new opportunities for convenience and competition.
A Bank for International Settlements working paper published in October 2026 compared costs across conventional banks, fintech transfer operators, and stablecoin-based systems. The researchers found that fintech operators generally offered substantially lower costs than traditional retail bank wires in the transactions examined. However, pricing continued to depend on currency pairs, transfer size, and payment arrangements.
The same study cautioned against assuming that stablecoins automatically eliminate cross-border payment expenses. Converting ordinary money into digital tokens, transferring them, and converting them back into local currency can involve trading charges, withdrawal fees, liquidity constraints, and compliance costs. Stablecoins may offer advantages in particular circumstances, but they are not a universally cheaper or safer solution.
For ordinary consumers, the practical choice remains comparing quotations from appropriately regulated providers. The technology used to process a payment matters less than its total cost, reliability, accessibility, and consumer protections.
How Consumers Can Reduce International Money Transfer Fees
Reducing unnecessary charges begins with comparing legitimate providers using the same transaction details. Consumers should examine the total amount paid, exchange rate, amount received, delivery time, and any disclosed third-party deductions. These details reveal more than promotional claims about zero-fee transfers or discounted services.
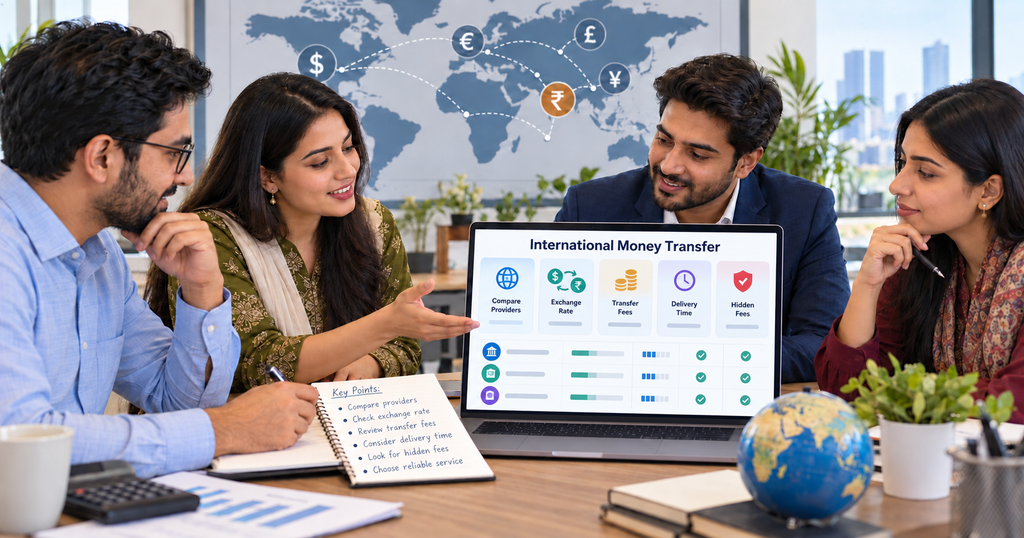
For recurring payments, customers should consider whether transfer frequency, funding method, or delivery speed affects costs. Standard delivery may be suitable when money is not urgently required, while choosing bank-account funding instead of an expensive card transaction can sometimes reduce charges. Existing customers should also review pricing periodically rather than assuming their usual provider remains competitive.
Security should remain part of every comparison. Consumers should verify that the provider is appropriately authorized, confirm recipient details, and review cancellation and complaint procedures before transferring substantial amounts. Unlicensed operators, unrealistic exchange-rate promises, and pressure to send money immediately can indicate elevated financial risk. A small saving is not worthwhile if it creates a serious possibility of fraud or nonpayment.
What to Do When Less Money Arrives Than Expected
When the recipient receives less than anticipated, the sender should review the transaction receipt, exchange rate, disclosed fees, and expected recipient amount. The receiving institution may also be able to identify an incoming payment charge or another deduction. Where the actual transaction differs from the provider’s disclosures, customers should request a written explanation and retain supporting records.
Consumer protections vary internationally. In the United States, certain qualifying remittance transfers are subject to federal disclosure and error-resolution rules. According to the Consumer Financial Protection Bureau, eligible transfers can generally be canceled without charge within 30 minutes of payment if the recipient has not already collected the money or received it in an account, subject to applicable conditions.
Readers in other countries should consult their relevant central bank, financial regulator, or consumer protection authority. Promptly reporting errors and preserving transaction documentation can improve the chances of resolving payment disputes.
Why Lower Remittance Costs Matter to the Global Economy
The economic consequences of expensive international transfers extend beyond individual senders. Remittances can contribute to household consumption, education, healthcare, and savings. When substantial fees are deducted, less money remains available for these purposes, potentially affecting families that rely on regular financial support from abroad.
The United Nations recognizes this challenge through Sustainable Development Goal 10.c, which aims to reduce migrant remittance transaction costs to below 3% by 2030 and eliminate remittance corridors charging more than 5%. The World Bank’s reported global average of 6.36% in the third quarter of 2025 indicates that the monitored global market remained above that target.
Achieving lower costs requires stronger competition, transparent pricing, efficient payment infrastructure, and appropriate consumer safeguards. Technology can contribute to these improvements, but effective regulation and reliable financial institutions remain important for protecting customers.
Final Thoughts
International money transfer fees can remain high because cross-border payments involve different currencies, financial institutions, processing methods, and regulatory requirements. The upfront charge represents only one component of the total expense. Exchange-rate markups, intermediary bank deductions, receiving fees, funding methods, and delivery arrangements can all influence the final amount. Understanding how these costs interact allows consumers to evaluate transfer services more accurately and avoid unnecessary financial losses.
Consumers can make better decisions by comparing total costs, verifying exchange rates, understanding applicable charges, and choosing trustworthy providers. The true value of an international money transfer is not determined by the advertised fee alone, but by how much money safely and reliably reaches its intended destination. Understanding that distinction can help families, freelancers, students, and businesses avoid unnecessary expenses.
Author’s Note
This article is intended for general educational and informational purposes and does not constitute financial, investment, legal, banking, tax, or regulated payment-service advice. International money transfer fees, exchange rates, payment availability, consumer rights, and regulatory requirements vary between countries, providers, and individual transactions and may change over time. Readers should verify current information directly with financial institutions and relevant authorities before making important financial decisions.
The discussion draws on publicly available research from recognized institutions, including the World Bank, Organisation for Economic Co-operation and Development, Bank for International Settlements, United Nations, and relevant consumer protection authorities. Numerical examples are hypothetical unless explicitly identified as institutional statistics. They are provided to illustrate financial concepts rather than represent live exchange rates, guaranteed transfer costs, or recommendations for particular service providers.
Busipulse approaches business, finance, and economic subjects from an independent educational perspective, emphasizing accuracy, balanced analysis, practical relevance, and accessible explanations. Readers are not required to agree with the author’s interpretations, assessments, or conclusions and are encouraged to examine the supporting evidence, consider alternative perspectives, and form their own informed judgments.
Busipulse publishes independent educational content examining business, finance, economics, consumer decisions, and developments affecting households and enterprises in the global economy.
[…] A bank transfer initiated outside normal processing hours may take longer if the relevant service operates on business-day schedules. Weekends, public holidays, or intermediary processing can also affect certain transfers, although these limitations do not apply to every digital payment system. For international transfers, processing delays should also be distinguished from transaction costs, including intermediary-bank charges and currency conversion. These additional expenses are examined in our guide to international money transfer fees. […]